How Ancillary Benefits Help Close Coverage Gaps
Getting a client enrolled in health insurance is important. But having health insurance does not mean every expense is covered. A hospital stay, accident, or serious illness can leave clients responsible for deductibles, co-pays, maximum out-of-pocket costs, and expenses that have nothing to do with the medical bill itself.
That is where ancillary benefits can become an important part of the conversation. In a recent Insurance Advisors Direct training, Scott Whittman of LifeSecure explained how agents can use Accident, Critical Illness, and Hospital Indemnity coverage alongside primary health insurance to help clients prepare for the financial gaps they may face.
More importantly, he explained how agents can make these conversations a natural part of the enrollment process.
What Are Ancillary Benefits?
Ancillary benefits are supplemental insurance products designed to complement a client’s primary health coverage. They do not replace major medical insurance. Instead, they can provide additional financial protection when certain covered events occur.
The training focused primarily on three types of coverage:
- Accident insurance
- Critical Illness insurance
- Hospital Indemnity insurance
Each addresses a different type of financial risk. Together, they can help agents build a broader protection strategy around a client’s primary Medicare or ACA coverage.
Health Insurance Does Not Eliminate Financial Risk
When agents review a health plan, it is natural to focus on the expenses printed in the Summary of Benefits. Deductibles. Co-pays. Maximum out-of-pocket costs. Hospital costs. Prescription costs.
Those expenses matter, but Scott encouraged agents to look below the surface. Imagine a client spends 10 days in the hospital. When that client returns home, life does not immediately return to normal. They may need someone to mow the lawn. They may need transportation. They may order meals because they cannot cook. They may miss work.
Their mortgage, rent, car payment, utilities, and other household expenses continue. The medical bill is only part of the financial impact. That is the coverage gap agents need to help clients understand.
Think Beyond the Medical Bill
One of the strongest lessons from the training was that a health event can affect much more than healthcare expenses. Scott described LifeSecure’s approach using three ideas:
Protect finances.
Provide for the unexpected.
Plan for the future.
That framework gives agents a simple way to think about ancillary coverage. The objective is not simply to pay another medical bill. It is to help clients maintain financial stability when an unexpected health event disrupts everyday life.
Hospital Indemnity Insurance Can Help With More Than Hospital Costs
Hospital Indemnity coverage is designed to provide benefits when a covered hospital event occurs, subject to the policy’s terms. One of the examples shared during the training showed why that flexibility can matter. Scott discussed a 67-year-old client who spent five days in the hospital.
According to the example, the client faced $1,625 in health plan cost sharing, lost $1,300 in wages, and needed to purchase a $250 air purifier. The client also had a Hospital Indemnity plan that paid $1,500.
Because the benefit was paid directly to the client, Scott explained that the money could be used to help with expenses such as his house payment and car payment while he made arrangements to address his medical cost sharing. That example demonstrates an important point. A client’s biggest concern after leaving the hospital may not be only the hospital bill. It may be keeping everyday life running.
Accident Insurance Helps Prepare for the Unexpected
Accidents happen quickly. A fall, broken bone, sports injury, or other unexpected event can send a client to urgent care, a doctor’s office, or the emergency room. Depending on the client’s primary health coverage, that can trigger deductibles and other out-of-pocket expenses.
LifeSecure’s Accident coverage discussed in the training is designed to provide benefits for eligible covered accidents according to the policy terms. Scott also explained that the product can be relevant for both ACA and Medicare clients. For families, accident protection can become especially important when children participate in sports and recreational activities.
Adults have risks too. Golf, softball, pickleball, household projects, falls, and everyday activities can all result in unexpected injuries. The conversation does not need to begin with product details. It can begin with a question:
If an accident caused you to reach a large portion of your health plan’s out-of-pocket maximum, how would you pay for it?
Critical Illness Coverage Addresses a Different Risk
An accident is unexpected. A serious diagnosis can be just as disruptive. Critical Illness insurance is designed to provide benefits following certain covered diagnoses, based on the policy’s terms.
During the training, Scott discussed conditions including cancer, heart attack, and stroke. The financial impact of a serious illness can extend well beyond treatment costs. Clients may miss work. Family members may need to take time away from their jobs. Transportation and household expenses continue.
There may also be costs associated with recovery. Scott summarized the goal clearly: clients should be able to focus on their health and getting better rather than worrying only about their finances. That is a simple way for agents to explain why Critical Illness coverage may deserve a place in the broader health insurance conversation.
Why Bundle Ancillary Benefits?
Accident, Critical Illness, and Hospital Indemnity coverage address different risks. That is why the webinar focused on bundling rather than treating each product as an isolated sale. Consider three common situations:
An accident occurs. Accident coverage may provide financial protection for a covered event.
A serious illness is diagnosed. Critical Illness coverage may provide benefits for an eligible covered diagnosis.
The client is admitted to the hospital. Hospital Indemnity coverage may provide benefits based on the policy.
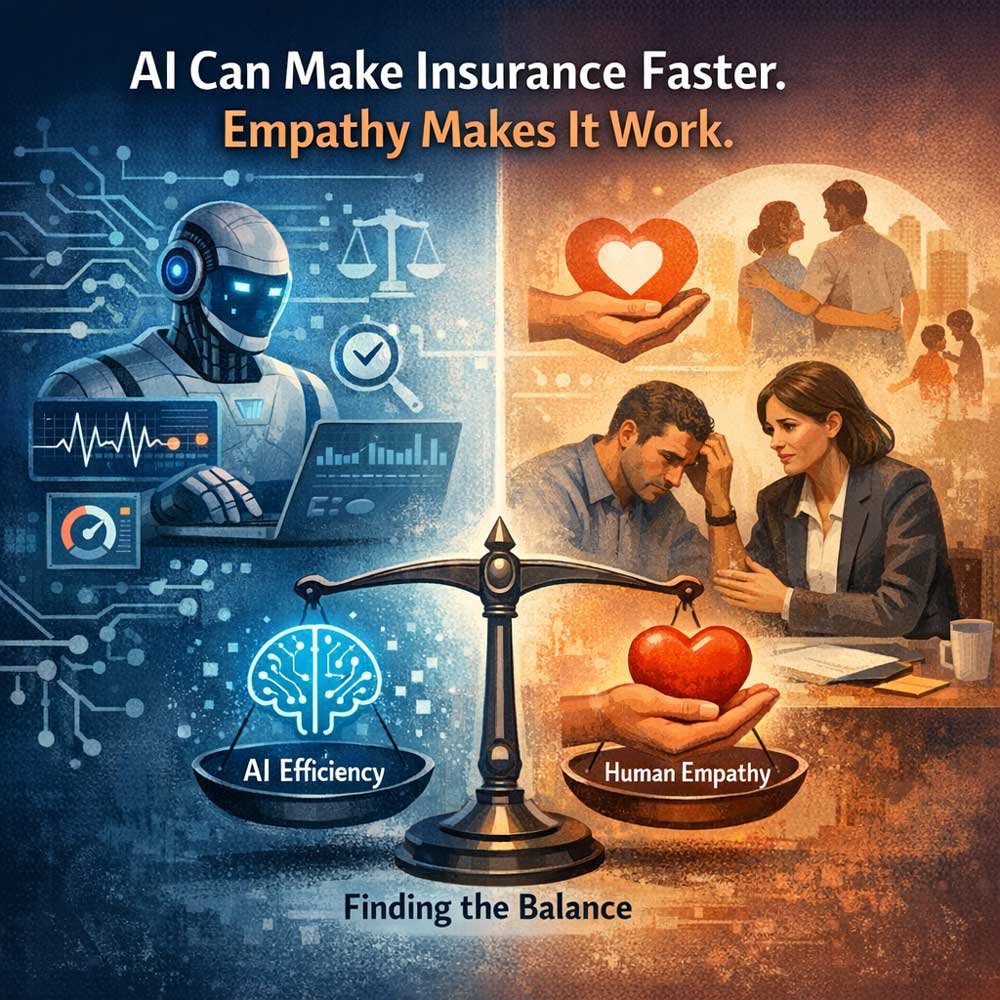
The client’s primary health insurance remains the foundation. Ancillary benefits can then be considered as additional layers of financial protection. The goal is not to add products simply for the sake of adding products. It is to identify the risks the client is concerned about and determine whether supplemental coverage may help address them.
Medicare Clients Can Have Coverage Gaps Too
Ancillary coverage is not only an ACA conversation. The webinar specifically discussed opportunities with Medicare clients. Medicare Advantage plans can include co-pays and maximum out-of-pocket exposure.
For clients living on fixed incomes, an unexpected hospital stay or other healthcare event can put pressure on their monthly budget. Hospital Indemnity and other supplemental products may provide another option for helping appropriate clients prepare for those expenses. Agents should review each client’s existing coverage, needs, eligibility, and financial situation before recommending additional insurance.
Start With Questions, Not Products
Toward the end of the training, Scott shared one of the most useful sales lessons of the entire session. Ask questions. Clients do not want to sit through another product presentation. They want someone to understand their concerns. Scott suggested starting with a simple question:
“What worries you about your current health insurance plan?”
You could also ask:
- What did you dislike about your coverage last year?
- Which healthcare expense concerns you most?
- How comfortable are you with your deductible?
- What would happen if you reached your maximum out-of-pocket amount?
- If you were hospitalized for a week, how would you handle your regular household expenses?
- How would missing work affect your finances?
Listen to the answers. Clients may tell you they are worried about the same issues the ancillary products are designed to address. That creates a much more natural conversation.
Sell the Problem You Solve, Not the Product
Scott used a simple analogy during the training. Millions of drill bits are sold, but people do not really want drill bits. They want holes. The same principle applies to insurance. Clients do not wake up wanting to buy Hospital Indemnity insurance. They want to know they can still pay their bills if they end up in the hospital.
They do not necessarily want Critical Illness insurance. They want greater financial confidence if they receive a serious diagnosis. They do not want an Accident policy simply because it is another policy. They want help managing the financial impact of an unexpected accident. That is why the conversation should focus on the problem first.
Do Not Wait Until the End of the Appointment
Another mistake discussed in the training is treating ancillary coverage as an afterthought. Imagine completing an entire Medicare or ACA enrollment and then asking as the client walks out:
“Do you want Hospital Indemnity too?”
That does not give the client enough context to understand why the coverage might matter. Instead, integrate the financial protection conversation into the health plan review. When discussing the deductible, talk about what would happen if the client had to pay it.
When reviewing hospital co-pays, ask how a hospital stay could affect their budget. When discussing the maximum out-of-pocket amount, ask whether they have savings available to handle that expense. Now ancillary coverage becomes part of solving a problem the client has already identified.
Keep the Conversation Simple
Agents may hesitate to discuss ancillary products because they worry the appointment will become too complicated or take too long. Scott’s advice was to practice integrating the conversation into every appointment.
The more often agents discuss these products, the easier the conversation becomes. He suggested that once the process becomes familiar, discussing ancillary protection may add only a few minutes to the overall presentation.
The key is consistency. Do not decide for the client that they cannot afford another option. Explain the potential gap, present an appropriate solution, and allow the client to make an informed decision.
Ancillary Benefits Can Strengthen Client Relationships
There is also a business reason for agents to understand supplemental products. IAD discussed how offering more complete protection can help strengthen client retention. If an agent handles the client’s primary health coverage and also helps address other financial risks, that agent may become a more valuable resource to the client.
That can lead to:
- Deeper client relationships
- Greater retention
- More complete coverage conversations
- Additional product opportunities
- Increased agent compensation when appropriate products are sold
But compensation should not drive the recommendation. The first question should always be whether the product addresses a legitimate client need.
A Simple Ancillary Conversation for Agents
Agents do not need an elaborate script to begin.
Start with:
“What worries you about your current health insurance?”
Then listen.
If the client says:
“My deductible.”
Ask:
“If you had to pay that tomorrow, would it create a financial problem?”
If the client says:
“My hospital costs.”
Ask:
“If you were hospitalized for several days, what other bills would you still need to pay while you recovered?”
If the client is concerned about a serious diagnosis, discuss how an illness could affect income and everyday expenses in addition to medical costs. The goal is not pressure. The goal is discovery.
Final Thoughts
Health insurance is the foundation of a client’s healthcare protection, but it may not address every financial consequence of an accident, serious illness, or hospital stay. That is why ancillary benefits deserve a place in the conversation.
Accident, Critical Illness, and Hospital Indemnity coverage can help appropriate clients prepare for specific financial risks their primary health plan may leave behind. For agents, the opportunity starts with one simple change.
Do not wait until the end of the appointment to ask whether the client wants another product. Start by asking what worries them. Understand the gap. Then discuss solutions that may help protect them. That is how agents move from simply enrolling health coverage to helping clients build a more complete protection strategy.
Learn How to Close the Coverage Gap
Want to see how these conversations work in practice?
Watch the full discussion with Scott Whittman to learn how Accident, Critical Illness, and Hospital Indemnity coverage can fit alongside Medicare and ACA plans, plus practical ways to introduce ancillary benefits during your existing enrollment process.
Insurance Advisors Direct helps independent life and health insurance agents grow with carrier access, contracting support, quoting tools, compliance resources, training, technology, and marketing support. We don’t just support agents. We partner with them.